
- Financial Planning for Major Life Events: Marriage to Job Loss (you are here)
- Divorce and Money: Why Equal Dollars Have Unequal Value
- Estimated Tax Safe Harbor: The Prior-Year Rule Explained
Big life events, like marriage, a baby, a divorce, a job loss or caring for a parent, change almost everything at once: your taxes, your health cover, who owns what, your debts and who inherits. Most come with a deadline, often 30 or 60 days. So do the paperwork first, such as health enrollment, a COBRA choice, your W-4 and beneficiary forms. Then rebuild your budget and emergency fund around your new household.
Why it matters: Missing a short deadline can cost you health coverage or leave the wrong person named as your beneficiary.
Summary: Every major life event changes your taxes, health coverage, ownership and debts, and heirs at once. Each has a deadline, usually 30 or 60 days, so do the paperwork first (health enrollment, COBRA election, W-4, beneficiary forms) and then rebuild the budget and emergency fund around the new household.
Throughout this volume we follow a single filer earning $75,000, paid $2,884.62 gross and $2,163.60 net every two weeks; in this chapter that household marries, has a child, is laid off and supports a parent.
- Marriage can cut tax or raise it: a one-earner $150,000 couple saves $9,394 in 2026, while two $75,000 earners see no change.
- A newborn is worth about $2,686 a year in tax and FSA savings to a single $75,000 parent, against early-years costs averaging $29,325.
- A 401(k) beneficiary form outranks a divorce decree.
- After a layoff, a 401(k) withdrawal before 55 costs $2,820.51 for every $10,000 spent in the 12% bracket; a 22.15% credit card costs more only if carried 28 months or longer.
There is no single correct account structure for a married couple — fully joint, fully separate, and a hybrid “yours, mine, and ours” (joint account for shared expenses, individual accounts for personal spending) are all workable, provided both partners understand and agree to whichever is chosen.
| Model | How it works | Works well when | Watch for |
|---|---|---|---|
| All joint | Both paychecks into one pool that pays everything | Similar habits; one partner earns little or nothing | Less privacy; one partner’s spending is both partners’ problem |
| Hybrid (“yours, mine, ours”) | Each pays an agreed share, equal or income-based, into a joint account for shared costs; the rest stays individual | Different spending styles; unequal incomes | The formula needs revisiting as incomes change |
| Fully separate | Separate accounts; shared bills split | Later marriages, children or assets from before | Shared goals drift; a non-earning spouse is exposed |
Credit stays individual. Marriage does not merge credit reports or scores (Part 3.1: How Credit Scores Actually Work). A joint account reports on both files, so a late payment marks both; authorized-user status (3.7) can help a thin file.
Taxes change. Filing status becomes married filing jointly or separately (Part 9.2). In 2026 every joint threshold up to the top of the 32% bracket is exactly double the single threshold, so the effect depends on how evenly income is split.
Wages only, standard deduction, 2026 federal tax.
- Couple A, two $75,000 earners. As singles, each has taxable income of $75,000 − $16,100 = $58,900 and tax of $1,240 (10% band) + $4,560 (12% band) + 22% × ($58,900 − $50,400) = $7,670; together $15,340. Married: $150,000 − $32,200 = $117,800 taxable; tax $2,480 + $9,120 + 22% × ($117,800 − $100,800) = $15,340. No penalty, no bonus.
- Couple B, $150,000 and $0. As a single filer the earner has $133,900 taxable and owes $1,240 + $4,560 + 22% × ($105,700 − $50,400) + 24% × ($133,900 − $105,700) = $24,734. Married, the same $15,340 as Couple A: a marriage bonus of $9,394.
The bonus comes from bracket width. Married, the earner’s income fills the non-earner’s unused 10% and 12% brackets; with equal incomes there is nothing unused to borrow.
Penalties appear where the joint figure is less than double. The top 37% bracket begins at $640,601 for single filers but only $768,701 for joint filers, so two $700,000 earners pay $10,250 more married than single. The 3.8% net investment income tax starts at $200,000 for a single filer but $250,000 for a couple (not indexed for inflation), and the $40,400 SALT cap is the same for a couple as for one person (9.2).
Health insurance. Marriage opens a special enrollment window: at least 30 days to add a spouse to an employer plan, and 60 days on the ACA marketplace. Compare both employers’ plans, including any spousal surcharge and whether one family plan with an HSA (Part 8.2) beats two self-only plans.
Debts. Debts brought into the marriage stay with their owner; joint debts belong to both. In the nine community-property states — Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington and Wisconsin — income earned and debt incurred during the marriage generally belong to both spouses; a few states, including Alaska, South Dakota and Tennessee, let couples opt in. Elsewhere, property and debt usually follow the name on them until a divorce (11.3).
Prenuptial agreements set, before the wedding, how property and debts will be divided at divorce or death — often to protect a business, an inheritance, or children from an earlier marriage. Courts look for full disclosure, time to consider, and ideally separate lawyers, and will not let one set child support. State law governs: this is a lawyer’s job.
Hold the money conversation before the wedding, not after a joint credit application surprises you. Cover:
- Disclosure — incomes, debts, credit scores, accounts.
- Structure — which model from the table.
- Goals — emergency fund (Part 1.4), home, children, retirement ages.
- Insurance — which health plan; whether life insurance is needed (Part 8.3).
- Paperwork — new beneficiary designations on retirement accounts and life insurance (12.1: Wills and Beneficiary Designations — Why Both Matter), which a marriage certificate does not update, and powers of attorney naming each other (12.2).
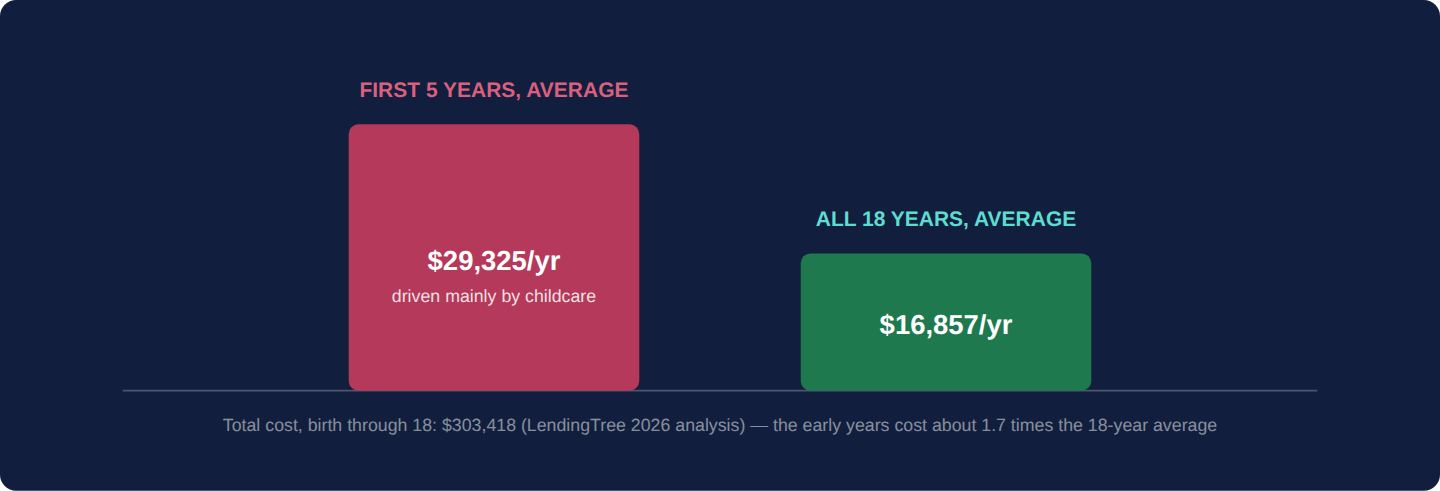
LendingTree’s 2026 analysis (the closest available successor to the U.S. Department of Agriculture’s discontinued annual report) puts the cost of raising a child from birth through age 18 at $303,418, averaging $16,857 a year — but that average conceals a front-loaded reality driven almost entirely by childcare.
Three earlier Parts directly soften this number: the Child Tax Credit is worth $2,200 per qualifying child for 2026, up to $1,700 of it refundable (Part 9.4), though LendingTree’s net figure already subtracts it; a Dependent Care FSA now shelters up to $7,500 of childcare costs pre-tax (Part 6.6, itself a 2026 OBBBA increase from $5,000), and a 529 plan (Part 4.4) can begin compounding from birth for costs a decade or more away. None of these fully offsets $303,418 — but together they materially change the real, after-benefit number a household actually needs to plan around.
A newer option arrived in 2026: Trump accounts (2025 OBBBA), with a one-time $1,000 federal deposit for U.S.-citizen children born 2025–2028 and up to $5,000 a year of contributions from Jul 4, 2026; Part 4.6 sets out the rules and how the account compares with a 529 plan (Part 4.4).
Take the running household as a single parent of a newborn, with the first-five-years average cost of $29,325 a year. Wages after the 401(k) and health premiums are $75,000 − $4,500 − $2,600 = $67,900, holding those deductions unchanged.
- Head of household filing — taxable income $67,900 − $24,150 = $43,750; tax 10% × $17,700 + 12% × ($43,750 − $17,700) = $1,770 + $3,126 = $4,896, versus $6,108 as a single filer: $1,212 saved.
- Dependent Care FSA of $7,500 — taxable income falls to $36,250, tax to $1,770 + 12% × $18,550 = $3,996, saving $900; the FSA also escapes FICA: 7.65% × $7,500 = $573.75.
The Child Tax Credit is not added again: LendingTree’s figures already subtract dependent tax credits and exemptions (for a married couple at the median family income). Total offsets: $1,212 + $900 + $573.75 = $2,685.75, so the net cost is about $29,325 − $2,686 ≈ $26,639 a year. Expenses paid through the FSA cannot also be claimed for the child and dependent care credit. Federal figures only; childcare prices vary widely by state.
Timing and overlap change the answers in 11.1 to 11.6.
| Situation | What changes | Why | Number or rule |
|---|---|---|---|
| Both spouses work after the wedding | Withholding is likely too low if each W-4 just says “married filing jointly” | Each employer applies the full joint standard deduction and brackets to one paycheck | Complete Step 2 of the 2026 W-4 on both jobs (the checkbox suits two jobs of similar pay) |
| Baby born on December 31 | The child counts for the whole year | A child born during the year is treated as living with you for the year if your home was its home | Full $2,200 Child Tax Credit (with a Social Security number); a single parent who pays over half the home’s costs can file as head of household |
| Leaving a job with a 401(k) loan outstanding | The unpaid balance is usually offset and treated as a distribution | The loan is repaid from the account when you leave | You can roll the amount over until your tax-return due date, with extensions; otherwise, for a 22%-bracket taxpayer under 55, a $15,000 offset costs $15,000 × (22% + 10%) = $4,800 |
| Laid off in or after the year you turn 55 | 401(k) withdrawals escape the 10% additional tax | The separation-from-service exception (age 50 for public-safety workers) | Applies to that employer’s plan only; rolling the money to an IRA first loses it |
| Paying COBRA while unemployed | An HSA can pay the premiums tax-free | COBRA and coverage while receiving unemployment benefits are qualified medical expenses | IRA withdrawals for health premiums also avoid the 10% tax after 12 weeks of unemployment pay |
| Freelancing alongside a W-2 job or a working spouse | Extra withholding can replace estimated payments | Withholding is treated as paid evenly through the year, whenever it was actually taken | A December W-4 increase can cover a full year’s shortfall without a penalty |
Divorce is governed by state law and every case turns on its facts; this is education about the financial mechanics, not legal advice.
Who owns what. The nine community-property states (11.1: Marriage — Merging (or Not Merging) Finances) generally treat property and debt acquired during the marriage as owned equally. The others use equitable distribution: a court divides marital property fairly, not necessarily 50/50. In both, property owned before the marriage or inherited usually stays separate — unless it was mixed into joint accounts.
Retirement accounts. Dividing a 401(k) or pension (Part 6, Part 10.4) requires a Qualified Domestic Relations Order (QDRO) — a court order distinct from the divorce decree, approved by the plan. A former spouse paid under a QDRO is taxed as the participant would be, can roll the money to their own IRA, and owes no 10% early-withdrawal tax on money paid directly from the plan. An IRA is split by a tax-free “transfer incident to divorce” that makes the share the recipient’s own IRA — but the 10% exception does not apply to IRAs, so cash taken before 59½ is penalized.
Taxes.
- Alimony under agreements executed after 2018 is neither deductible nor income — the reverse of the old rule. The change has no expiry date and applies as of Oct 2026; older agreements keep the old treatment unless a modification adopts the new one.
- Child support is never deductible and never income.
- Filing status is set on Dec 31: with a final decree by then, you are unmarried for the whole year.
- Children — the custodial parent claims them; Form 8332 can pass the Child Tax Credit to the other parent, but not head-of-household status or the earned income credit.
- Property transfers between spouses in a divorce are tax-free, but the recipient inherits the original cost basis and its built-in gain.
The house can be sold, or kept by one spouse buying out the other. Keeping it usually means refinancing into one name, qualifying on one income at current rates (Part 5). Removing a name from the deed does not remove it from the mortgage; only a refinance, a sale, or a lender’s release (if the loan is assumable) does.
Health and benefits. A spouse covered by the other’s employer plan can keep it through COBRA for up to 36 months after a divorce, but must notify the plan within 60 days. An ex-spouse married at least ten years may claim Social Security on the former partner’s record (10.8). Update beneficiary designations and estate documents promptly (12.1: Wills and Beneficiary Designations — Why Both Matter).
Two questions on this chapter. Decide on your answer first, then click “Reveal Answer.”
1. One partner earns $120,000 in wages and the other earns nothing. Using 2026 federal brackets and standard deductions, how much less federal income tax do they owe married filing jointly than the earner would owe filing single?
- $5,288
- $7,530
- $10,040
- $0
Reveal Answer
Answer: B. Single: $103,900 taxable, tax $1,240 + $4,560 + 22% × $53,500 = $17,570. Joint: $87,800 taxable, tax $2,480 + 12% × $63,000 = $10,040. Bonus $7,530. $0 is the equal-earner case, $5,288 uses the single deduction, $10,040 is the joint tax itself. (Part 11.1: Marriage — Merging (or Not Merging) Finances)
2. Tom’s divorce decree says his former wife gives up any claim to his 401(k), but he never changes the plan’s beneficiary form, which still names her. He dies. Under the case the chapter describes, who receives the account?
- His estate, because the divorce decree overrides the plan’s form
- Each gets half under the state’s marital property rules
- His former wife, as the beneficiary named on the plan’s form
- His children, as his closest heirs under state law
Reveal Answer
Answer: C. ERISA requires the plan to pay according to its documents; in Kennedy v. Plan Administrator for DuPont (2009) the Supreme Court upheld paying about $400,000 to an ex-wife who had waived it in the decree but was still named on the form. (Part 11.3)
- Trump accounts — Accounts for children
- Topic 418: unemployment compensation — Taxation of unemployment benefits
- COBRA coverage and the Marketplace — Switching rules
- Child Tax Credit — CTC phase-outs
- Form 1040-ES (2026) — Estimated tax due dates
- Topic 306: underpayment penalty — Safe harbors